
Markus Pelger
Bio
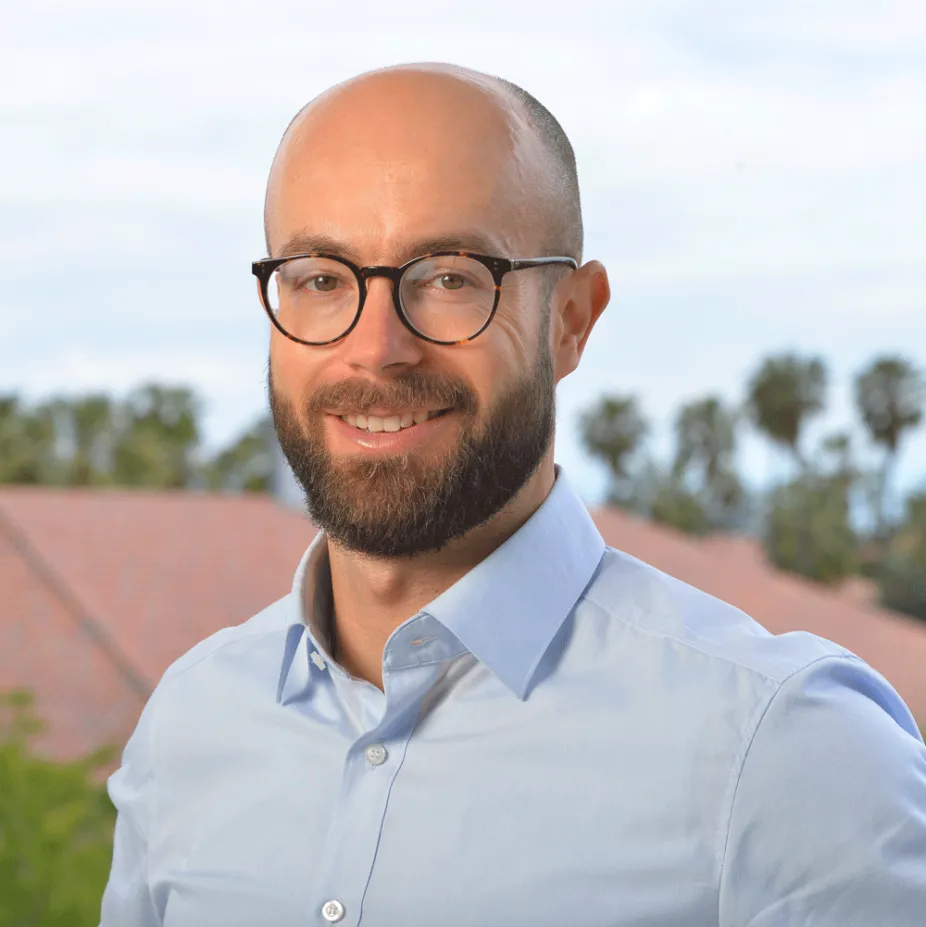
Markus Pelger is an associate professor of management science and engineering at Stanford University, a Chambers Faculty Scholar in the School of Engineering and the director of the Stanford Advanced Financial Technologies Laboratory (AFTLab). He is also an associate professor of finance (by courtesy) at Stanford Graduate School of Business and a research associate at the National Bureau of Economic Research.
His research on machine learning and statistical methods in finance has appeared in the Journal of Finance, the Review of Financial Studies, the Journal of Financial Economics, Management Science, and the Journal of Econometrics. Pelger’s research has been recognized with the Best Paper Award at the Utah Winter Finance Conference, the Best Paper in Asset Pricing Award at the SFS Cavalcade, the Dennis J. Aigner Award of the Journal of Econometrics, the Bates-White Prize of the Society for Financial Econometrics and the Engle Prize of the Journal of Financial Econometrics. He is an associate editor of Management Science, the Review of Finance, the Journal of Econometrics, the Journal of Financial Econometrics and Operations Research, and a co-founder and co-organizer of the AI & Big Data in Finance Research Forum. He has presented his research at more than 200 seminars and conferences and has been a consultant to investment institutions, the Federal Reserve Banks of Dallas and San Francisco and the International Monetary Fund.
Pelger received his PhD in Economics from the University of California, Berkeley, and Diplom degrees in Mathematics and in Economics, both with distinction, from the University of Bonn in Germany. He joined the Stanford faculty in 2015.
Research Interests
- Asset pricing
- AI and machine learning in finance
- Financial econometrics
- Fixed income
- Financial technology
Academic Degrees
- PhD in Economics, University of California, Berkeley, 2015
- Diplom in Mathematics, University of Bonn (Germany), 2012
- Diplom in Economics, University of Bonn (Germany), 2009
Academic Appointments
- Associate Professor of Finance (by courtesy), Stanford Graduate School of Business, 2026–present
- Associate Professor of Management Science and Engineering (with tenure), Stanford University, 2024–present
- Assistant Professor of Management Science and Engineering, Stanford University, 2015–2024
- Research Associate, National Bureau of Economic Research (Asset Pricing)
Professional Experience
- Consultant, International Monetary Fund
- Consultant, Federal Reserve Bank of Dallas
- Consultant, Federal Reserve Bank of San Francisco
- Consultant, AllianceBernstein
- Consultant, Migdal
Research Statement
Teaching Statement
Teaching Materials
Videos and Podcasts
-
Shrinking the Term Structure
Risk Seminar, Consortium for Data Analytics in Risk, University of California, Berkeley, April 2024.
 01:17:29
Shrinking the Term Structure
-
Stripping the Discount Curve: A Robust Machine Learning Approach 00:51:25
Stripping the Discount Curve: A Robust Machine Learning Approach
-
Missing Financial Data 00:21:13
Missing Financial Data
-
Machine-Learning the Skill of Mutual Fund Managers 00:28:56
Machine-Learning the Skill of Mutual Fund Managers
-
Deep Learning Statistical Arbitrage
Risk Seminar, Consortium for Data Analytics in Risk, University of California, Berkeley, September 2021.
01:24:07Deep Learning Statistical Arbitrage
-
Deep Learning in Asset Pricing
Utah Winter Finance Conference, 2020.
00:27:47Deep Learning in Asset Pricing
Documents, Presentations, and Multimedia
-
Chair of the invited panel, American Finance Association Annual Meeting, Washington, D.C.
-
NVIDIA webinar, August 2020.